In volume, yes. China installed 295,000 industrial robots in 2024, 54 percent of everything installed worldwide, and Chinese brands now outsell foreign ones in their home market. In humanoids, China has more companies building working machines than any other country. At the very top end of precision parts and in some software layers, Europe, Japan and the US still lead. The lead is real, but it is uneven.
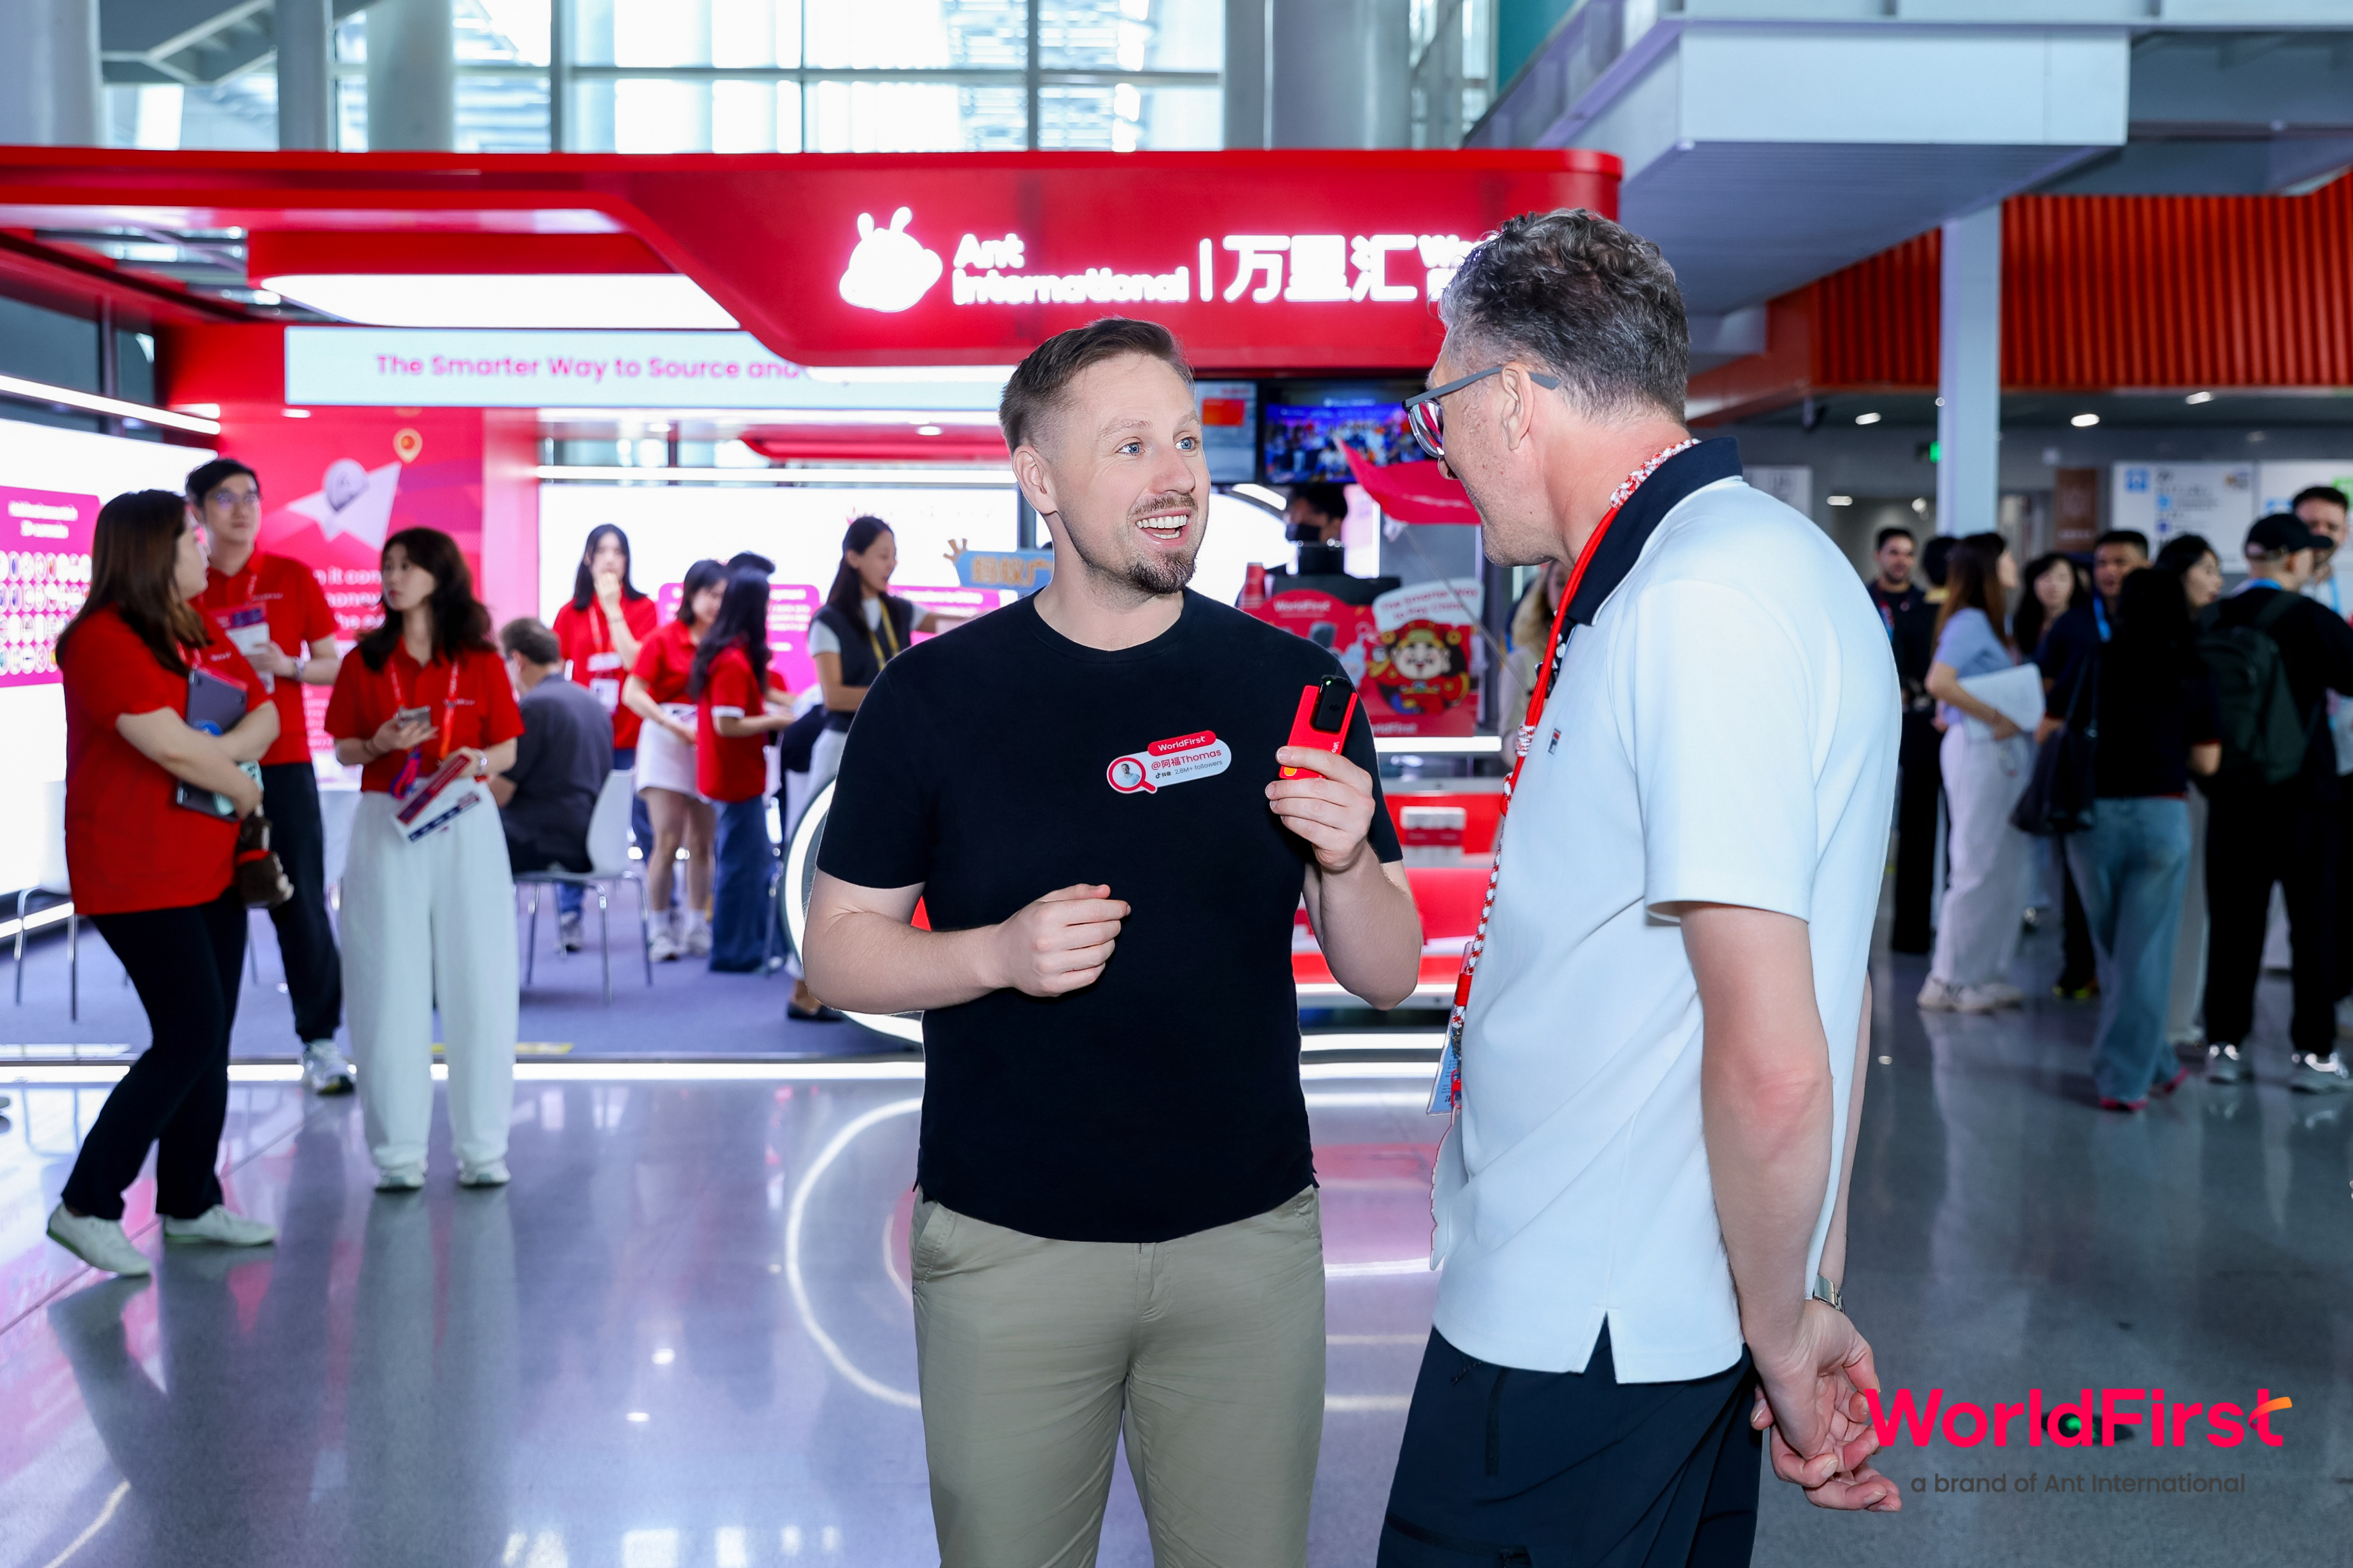
I'm Thomas Derksen. I have lived in China for more than twelve years, and with Asiabits I spend most weeks inside Chinese robotics companies, usually with a European leadership team next to me. The question in the title is the one I get asked most, in boardrooms in Munich and on factory floors in Suzhou. Here is how I answer it, with the numbers we track ourselves and what I see when I walk the lines.
How big is China's lead in industrial robots?
The International Federation of Robotics publishes the most reliable count. Its World Robotics 2025 report puts China at 295,000 new industrial robots in 2024, a record, and an operational stock of more than two million units. For the first time, Chinese manufacturers sold more robots in China than foreign suppliers did, with a domestic market share of 57 percent.
Germany, for comparison, installed 26,982 units in the same year. That makes it the largest market in Europe and number five in the world. On robot density, which counts robots per 10,000 manufacturing workers, Germany sits at 449 and ranks fourth globally. Density rewards a mature industrial base. Installations show where the next factories are being built.
So on industrial arms, China is ahead on the measure that tells you about the future. A decade ago Chinese factories bought robots from Japan and Germany. Today most of them buy from Chinese makers, and those makers use the home market as a training ground before they export.
What does our own data show?
At Asiabits we keep a database of more than 7,000 robotics companies. The China slice is the largest part of it: 2,217 companies. Of those, 159 are classified as humanoid robot makers. The next largest group in our data is the United States with 20.
Our database started in Asia and grew from there, so it sees Chinese companies more completely than American or European ones. The ratio between China and the US is certainly smaller in reality. But even if you halve the China number, the gap stays wide. When I go to a robotics expo in Beijing or Shenzhen, I walk past more humanoid booths in one hall than I would find at a major European fair in total.
The more interesting number for me sits one level down. We count 461 Chinese companies in the components category: reducers, servo motors, actuators, force and torque sensors. Germany has 106 in the same category in our data. These are the companies that decide what a robot costs, and that is where the shift is happening.
Where is China still behind?
Ask a Chinese humanoid founder over dinner where the hardest problems are, and you will hear the same short list. High-precision reducers that hold their tolerance for years. Six-axis force sensors at the top of the accuracy range. Chips for on-robot compute. Some of these still come from Japan, Germany, Switzerland or the US, especially in the premium models.
This summer we took the leadership team of a German automotive electronics supplier through a dozen Chinese robot makers in five days. At almost every stop, the engineers named two problems without being prompted: the robots are too heavy, and they run too hot. Those are engineering problems in thermal management and lightweight construction. European suppliers have been solving them for cars for decades.
Then there is the gap between demo and deployment. I wrote about this after asking ten humanoid companies at one expo what their robots do for paying customers. Several had a clear answer. Many did not yet. China builds faster than it deploys, and a large share of today's humanoids are still sold to research labs, universities and showrooms.
Capital follows a similar pattern. According to PitchBook figures cited by Georgetown's CSET, about $20.5 billion went into warehouse robotics over five years and about $4.6 billion into humanoids. The money that expects a return this decade still goes to robots that pick and sort.
Why does China move so fast?
Three things come together, and you can see all of them within a two-hour drive of Shanghai.
First, the supply chain is shared with electric vehicles. The motors, batteries, power electronics and sensors in a humanoid overlap heavily with what goes into an EV. The Yangtze River Delta put millions of EVs on the road, and the same suppliers now run humanoid pilot lines next door. Every time EV volume pushes a component price down, robotics benefits.
Second, distance. Joshua Woodard, who managed camera production for a large American electronics brand in Shenzhen, told me on our podcast that a problem that takes a week to solve in America gets solved in a day in Shenzhen, because every expert you need is close enough to meet that afternoon. I see the same thing in robotics. A founder can change a gearbox supplier on Monday and test the new part on Thursday.
Third, price discipline. When UBTech started delivering humanoids at a published price, it told the market that the cost curve is now public. Competitors have to answer it. That pressure works through the whole chain, down to the smallest actuator supplier.
Does China lead in humanoid robots specifically?
In the number of companies, the number of units shipped and the speed of iteration, I would say yes. In the quality of the best individual machine, the answer depends on the task, and several American and European teams are very strong on the AI side.
What strikes me on visits is how quickly a Chinese team goes from one prototype to the next. A company shows you version three in spring and version five in autumn. That pace comes from cheap parts, fast suppliers and a domestic market that buys early, often with support from local governments that want a robotics cluster in their city.
Policy matters too. Beijing has said clearly that it wants to lead in AI-powered robots built at scale, and provinces compete for those companies with land, subsidies and early orders. That is one reason I call this the next China shock for European industry. It will arrive one component at a time, as Chinese suppliers take over parts that used to ship from Germany, Switzerland or Japan.
What does this mean for European companies?
I spent two weeks in Germany this summer visiting robotics companies and suppliers, and I came back more optimistic than I left. Germany has engineering depth and an automotive supplier base that matches exactly what humanoid makers are short of. There are no settled standards yet for humanoid interfaces, sensor specs or module formats. Whoever helps write them early sits inside every robot built afterwards.
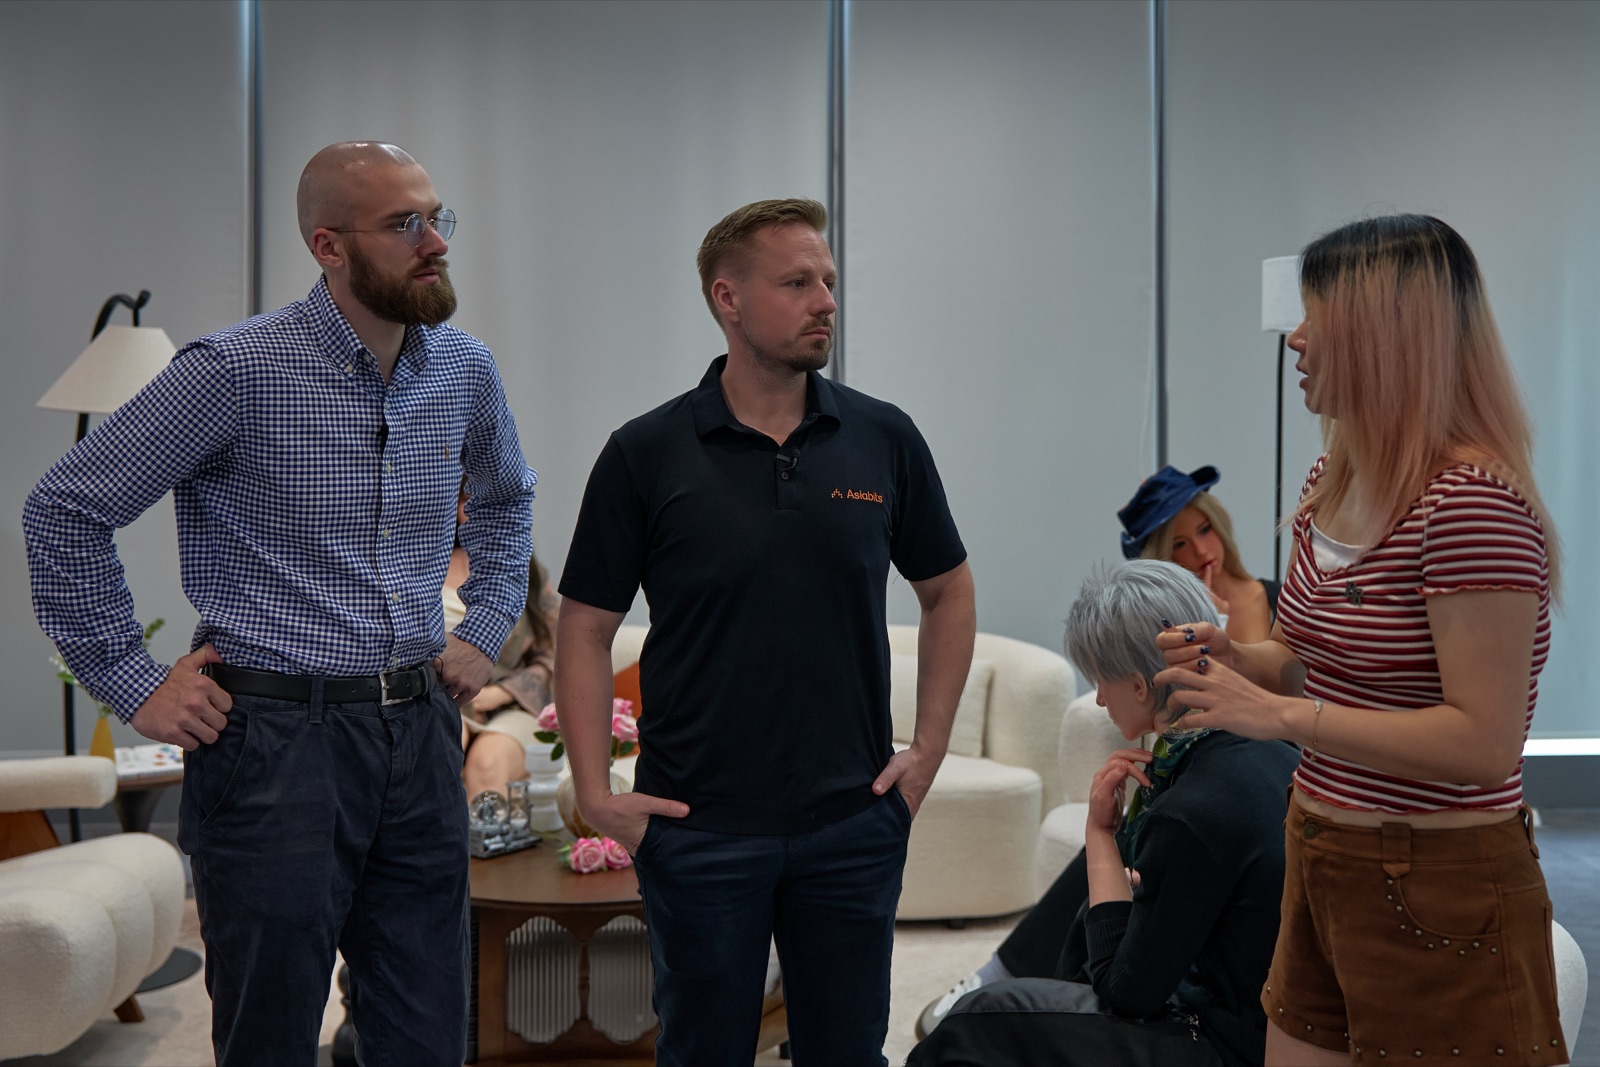
The companies I see doing well treat China as a partner market and a benchmark at the same time. They come over, sit across the table from the founders, look at the bill of materials and find the two or three places where their product solves a problem the Chinese team has today. A European fashion retailer with stores in 47 countries sent its CEO and three executives to a humanoid maker's headquarters with us, and they flew home with an implementation plan. A specialty chemicals group used its visit to understand where its materials fit in robot production. In both cases, the visit shortened a decision that would otherwise have taken a year of reports.
The pattern on these visits is consistent. The European side arrives expecting to evaluate a supplier. Within an hour the Chinese founder is asking them questions about tolerances, certification and service networks in Europe, because that is what they need to sell abroad. Both sides leave with a list of what the other one can do. Most of the useful follow-up starts with a sample order or a joint test, and rarely with a big contract.
The companies that struggle wait for the market to become clear. By the time it is clear, the supply relationships are already set.
How can you check this yourself?
Reports help, but this industry changes faster than reports can follow. My practical advice is to start with the public data and then go and look. Our free Asia Robotics Directory lists 2,562 companies and 4,173 investors you can filter by category and stage. The China Robot Supply Chain Map shows 260 companies across 18 tiers, from actuators to foundation models, so you can see where your own product would sit.
If you want to see it in person, Asiabits runs private robotics factory tours and delegations in Shanghai, Shenzhen, Hangzhou and Suzhou. We pick the companies around your question, I chair the meetings in Mandarin and English, and your team spends its time on production floors and with founders. If you are weighing whether China is ahead in the part of robotics that matters to your business, one focused day there will give you the answer for your own business.
Frequently asked questions
Is China the world leader in industrial robots?
By installations, yes. According to the IFR, China installed 295,000 industrial robots in 2024, 54 percent of the global total, and has an operational stock of more than two million units. Countries like South Korea, Singapore and Germany still have a higher robot density per manufacturing worker.
How many humanoid robot companies are there in China?
Asiabits tracks 159 Chinese companies classified as humanoid robot makers in its database of more than 7,000 robotics companies, far more than any other country in the data. The exact number moves every month as new startups launch and others merge or close.
Where is China still behind in robotics?
At the top end of precision components such as high-accuracy reducers and six-axis force sensors, in some compute chips, and in turning humanoid demos into paid deployments. Many premium Chinese robots still use parts from Japan, Germany, Switzerland or the US.
Why is China moving so fast in robotics?
The robotics supply chain overlaps heavily with electric vehicles, suppliers sit close together in regions like the Yangtze River Delta and Shenzhen, and a large domestic market buys early. Government support at national and provincial level adds pressure and capital.
What should European companies do about China's robotics lead?
Find out where their own products fit in the Chinese robot supply chain, especially in thermal management, lightweight construction, sensors and precision parts. Visiting the companies directly is the fastest way to learn which problems Chinese robot makers need solved.
Get These Insights Every Monday
Join 18,000+ professionals reading Asiabits. Free, every Monday, straight from Shanghai.
Subscribe Free →